Adroit Industries (India)
Engineering Motion PreciselyDriving Engineering Forward
IPO Summary (PreQT)
Adroit Industries (India) Limited is a vertically integrated manufacturer of propeller shafts and torque-transmission components, with capabilities spanning forging, heat treatment, precision machining, assembly, balancing, finishing and testing. Established in 1966, the Company operates three manufacturing facilities in Madhya Pradesh at Dewas, Pithampur and Sanwer, offering 5,250 SKUs as of July 2026 across automotive, off-highway, defence and industrial applications.
The business is primarily export-driven and distributor-led. In FY26, 95.4% of sale-of-products revenue came from exports, with distributors contributing 62.5%, Tier-1 driveline suppliers 32.9% and OEMs 4.7%. The Company exported to 32+ countries, with the US accounting for 53.8% of export revenue. Repeat customers contributed 90.3% of FY26 product revenue.
The IPO comprises 1,12,47,000 shares at INR 126–134 per share, including INR 132.6 Cr fresh issue and INR 18.1 Cr OFS at the cap price. Fresh proceeds will fund capex, subsidiary debt repayment and general corporate purposes.
IPO Review Rating
Above Avg
MainboardBuilding Reliable Propeller Shaft Solutions for Automotive and Industrial Applications
The Company's key strength is profitability and capital efficiency rather than top-line growth. FY24–FY26 Revenue CAGR was only 6.0%, while EBITDA margin expanded from 23.8% to 27.7%, PAT margin from 11.7% to 18.7%, RoNW reached 22.5%, and D/E declined from 0.94x to 0.41x. FY26 operating cash flow of INR 29.4 Cr exceeded PAT of INR 26.2 Cr, indicating strong earnings conversion.
Adroit has a diversified global footprint, with 95.4% of product revenue generated through exports across 32+ countries. However, geographical and customer concentration remain key risks, with the US contributing 53.8% of FY26 export revenue and the top 10 customers accounting for 60.9% of product revenue. FX volatility, US trade policies and tariffs warrant monitoring.
Governance metrics are relatively strong, with 60.0% Board independence, zero promoter pledge and 71.9% continuing Promoter + Promoter Group ownership post-IPO. Related-party transactions and exposure to Signet Industries require attention.
The key concern is valuation: at INR 134.0, P/E is 23.0x versus the disclosed peer average of 15.8x, implying a 45.5% premium.
PARAMETER
WEIGHT
SCORE
KEY FACTORS
Financial Performance
40.0%
4.0/5
Adroit's headline Revenue growth is only 6.0% CAGR, but the quality underneath the income statement has improved considerably. EBITDA margin of 27.7%, PAT margin of 18.7%, RoNW of 22.5%, declining leverage and OCF exceeding PAT create a strong financial profile. Customer concentration and the very long working-capital cycle remain the primary offsets
Show more
Detailed Analysis
Revenue increased from INR 124.5 Cr in FY24 to INR 139.9 Cr in FY26, implying a moderate 6.0% CAGR
FY26 EBITDA was INR 38.7 Cr, with an exceptionally healthy 27.7% margin, up from 23.2% in FY25
FY26 PAT was INR 26.2 Cr, translating into a strong 18.7% PAT margin, versus 13.6% in FY25 and 11.7% in FY24
D/E improved materially from 0.9x in FY24 to 0.4x in FY26
FY26 RoNW was 22.5%, compared with 18.9% in both FY25 and FY24
FY26 OCF was INR 29.4 Cr, exceeding PAT of INR 26.2 Cr; OCF was also positive in FY24 and FY25
Top 10 customers contributed 60.9% of FY26 Sale-of-Products Revenue and the largest customer contributed 20.9%
Industry
15.0%
3.0/5
The industry offers moderate structural growth rather than high-growth characteristics. India has attractive export and manufacturing advantages, and Adroit's multi-country presence is a major positive. The principal long-term industry risk is electrification changing traditional drivetrain architecture, alongside tariffs and export-market dependence
Show more
Detailed Analysis
Global propeller-shaft demand is estimated to grow at approximately 6.0% CAGR during 2020–30; Indian automobile exports grew at ~10.0% CAGR during FY21–FY26
Emission standards, drivetrain electrification, trade tariffs and export-market regulations can materially alter product demand and pricing
Adroit already exports to 32+ countries, while Indian auto components benefit from global sourcing and India's manufacturing-cost position
Management
15.0%
4.0/5
Adroit benefits from long-standing promoters, 60.0% independent Board representation, zero promoter pledge and high continuing ownership after listing. The principal governance monitors are related-party exposure to Signet Industries and certain promoter/tax proceedings
Show more
Detailed Analysis
The business dates to 1966; Saurabh Sangla has 18+ years of broader manufacturing experience and Mukesh Sangla has 40+ years of industrial experience
3 of 5 Directors are Independent i.e 60.0%, including a woman Independent Director
Promoters have no pledged Adroit shares; however, promoter-related litigation and tax matters warrant monitoring
FY26 related-party sales and purchases with promoter-linked entities are material but not dominant; investments in Signet Industries are also sizeable
Valuation
20.0%
3.0/5
Valuation is the principal score constraint. 23.0x post-Issue P/E represents a 45.5% premium to the disclosed peer average, despite Adroit's Revenue CAGR being only 6.0%. The counterargument is the Company's materially superior 27.7% EBITDA margin, 18.7% PAT margin and 22.5% RoNW
Show more
Detailed Analysis
23.0x post-Issue P/E versus 15.8x peer average, a 45.5% premium
Comparable current enterprise values for all RHP peers are not disclosed consistently enough for a defensible comparison.
FY26 historical NAV is INR 36.8/share, but final post-Issue NAV is not disclosed and issue expenses remain unfinalized
FY26 RoNW is a healthy 22.5%, up from 18.9% in FY24/FY25
Merchant Banker Track Record
10.0%
5.0/5
Choice Capital brings a good recent execution and listing record, with particularly strong subscription levels across its recent mainboard mandates. The principal limitation is the relatively smaller and more mixed mainboard/SME sample
Show more
Detailed Analysis
A 10-issue recent listed sample indicates approximately 18.4% average listing gain, although SME IPOs materially influence the average
Choice's recent mainboard issues have generally received strong subscription; its 2025 mainboard mandates were all subscribed well above 50x
9 of the 10 recent listed issues in the reviewed sample opened above issue price
TOTAL
100%
3.8/5
Weighted Composite Score
Issue Price
₹126.0 to ₹134.0
As of 22 Sep 2026
GMP
₹26.0
As of 22 Sep 2026
Estimated Gain / Loss
+19.4%
Lot Size
111.0 Shares
Grey Market Premium (GMPs) are shared for knowledge purpose only. PrEqt doesn’t promote or execute the trades.
| Issue size | |
|---|---|
| Overall | ₹151.0 Cr |
| Fresh Issue | ₹133.0 Cr |
| Offer for Sale | ₹18.0 Cr |
Minimum Investment
₹14,874.0 / 12,321 shares

Merchant Banker
Choice Capital Advisors Pvt.Ltd.
Choice Capital Advisors Pvt.Ltd.
IPO Document
Offer Start Date
Offer End Date
Valuation
Revenue (FY'26)
PAT (FY'26)
Issue Size
Face Value
₹ 10.0Offer Price
₹ 134.0Lot Size
111.0 sharesSale Type
Fresh capital cum OFSPAT (FY'26)
₹ 26.2 CrPAT Margin (FY'26)
18.7 %P/E Multiple
23.0xEBITDA (FY'26)
₹ 38.7 CrCAGR Growth 2Y
6.0 %ROE (FY'26)
22.5 %ROCE (FY'26)
19.0 %Debt/Equity
0.4xCompany Website
www.adroitindustries.comExplore new deals
Overview
Fund Allocation
Total: ₹0 CrSource:Company DRHP
Timeline
IPO Open Date
To Be Announced
IPO Close Date
To Be Announced
Tentative Allotment
To Be Announced
Initiation of Refunds
To Be Announced
Credit of Shares to Demat
To Be Announced
Tentative Listing Date
To Be Announced
Business
Products
Business Model
Geographical Presence
Sales Channel
Key Risk Factor
Financial Highlights
Income Statement
Revenue growth with EBITDA and PAT margins
| Financial Metric | FY 2024 | FY 2025 |
|---|---|---|
| Revenue (₹ Cr) | 124.5 | 133.9 |
| Growth (%) | - | 7.5% |
| EBITDA (₹ Cr) | 29.7 | 31.0 |
| EBITDA Margin (%) | 23.8% | 23.2% |
| PAT (₹ Cr) | 14.5 | 18.1 |
| PAT Margin (%) | 11.7% | 13.6% |
OBSERVATIONS & INSIGHTS
Revenue from operations increased 7.5% in FY25 and 4.5% in FY26, indicating steady but moderate top-line growth rather than rapid scale expansion
EBITDA increased 24.8% in FY26 despite revenue growth of only 4.5%, driving EBITDA margin expansion to 27.7% from 23.2% in FY25
PAT increased from INR 14.5 Cr in FY24 to INR 26.2 Cr in FY26. FY26 PAT growth of 44.2% materially exceeded revenue growth, supported by stronger operating profitability and lower finance costs
PAT margin improved consistently from 11.7% in FY24 to 18.7% in FY26, while EBITDA margin reached 27.7%, indicating improved profitability over the three-year period
Balance Sheet
| Financial Metric | FY 2024 | FY 2025 | FY 2026 |
|---|---|---|---|
| Net Worth | ₹ 87.8 Cr | ₹ 103.5 Cr | ₹ 128.6 Cr |
| Total Assets | ₹ 199.4 Cr | ₹ 187.0 Cr | ₹ 212.7 Cr |
| Total Borrowing | ₹ 81.9 Cr | ₹ 64.8 Cr | ₹ 52.4 Cr |
| Reserves & Surplus | ₹ 70.4 Cr | ₹ 86.1 Cr | ₹ 93.7 Cr |
OBSERVATIONS & INSIGHTS
Net worth increased from INR 87.8 Cr in FY24 to INR 128.6 Cr in FY26, while total borrowings declined from INR 81.9 Cr to INR 52.4 Cr, materially strengthening leverage
Total assets increased to INR 212.7 Cr in FY26; trade receivables of INR 45.3 Cr and inventory of INR 55.2 Cr remained major components of the asset base
The FY24-FY26 balance-sheet trend therefore combines a stronger equity base and lower debt with continued working-capital intensity
Cash Flow
| Financial Metric | FY 2024 | FY 2025 | FY 2026 |
|---|---|---|---|
CFO (₹ Cr) Cash generated from core business operations. | +19.9 Cr | +20.3 Cr | +29.4 Cr |
CFI (₹ Cr) Cash used for investments and long-term assets. | -0.5 Cr | +3.2 Cr | -12.1 Cr |
CFF (₹ Cr) Cash flow related to funding and borrowings. | -19.7 Cr | -23.5 Cr | -17.0 Cr |
Working Capital
| Efficiency Metric | FY 2023 | FY 2024 | FY 2025 |
|---|---|---|---|
Debtor Days Average number of days taken to collect customer payments. | - | - | - |
Creditor Days Average time taken to pay suppliers and vendors. | - | - | - |
Inventory Days Average number of days inventory remains unsold. | - | - | - |
CCC (Cash Conversion Cycle) (Debtor Days + Inventory Days - Creditor Days) | - | - | - |
Financial Ratios
Measures the company’s leverage relative to shareholder equity.
OBSERVATIONS & INSIGHTS
ROE remained around 19.0% in FY24-FY25 before increasing to 22.5% in FY26 as profit growth exceeded the expansion in the equity base
Debt/Equity reduced from 0.9x in FY24 to 0.4x in FY26, reflecting lower borrowings and a stronger net-worth base
Interest Coverage improved from 3.2x in FY24 to 8.1x in FY26 as finance costs declined and operating profit increased
Current Ratio improved from 1.2x in FY24 to 1.5x in FY26, although the current-asset base remains heavily represented by inventory and receivables
The closing-balance ROA proxy improved to 12.3% in FY26 and RHP ROCE increased to 19.0%, indicating better utilisation of the asset and capital base
Industry Overview
Industry Drivers
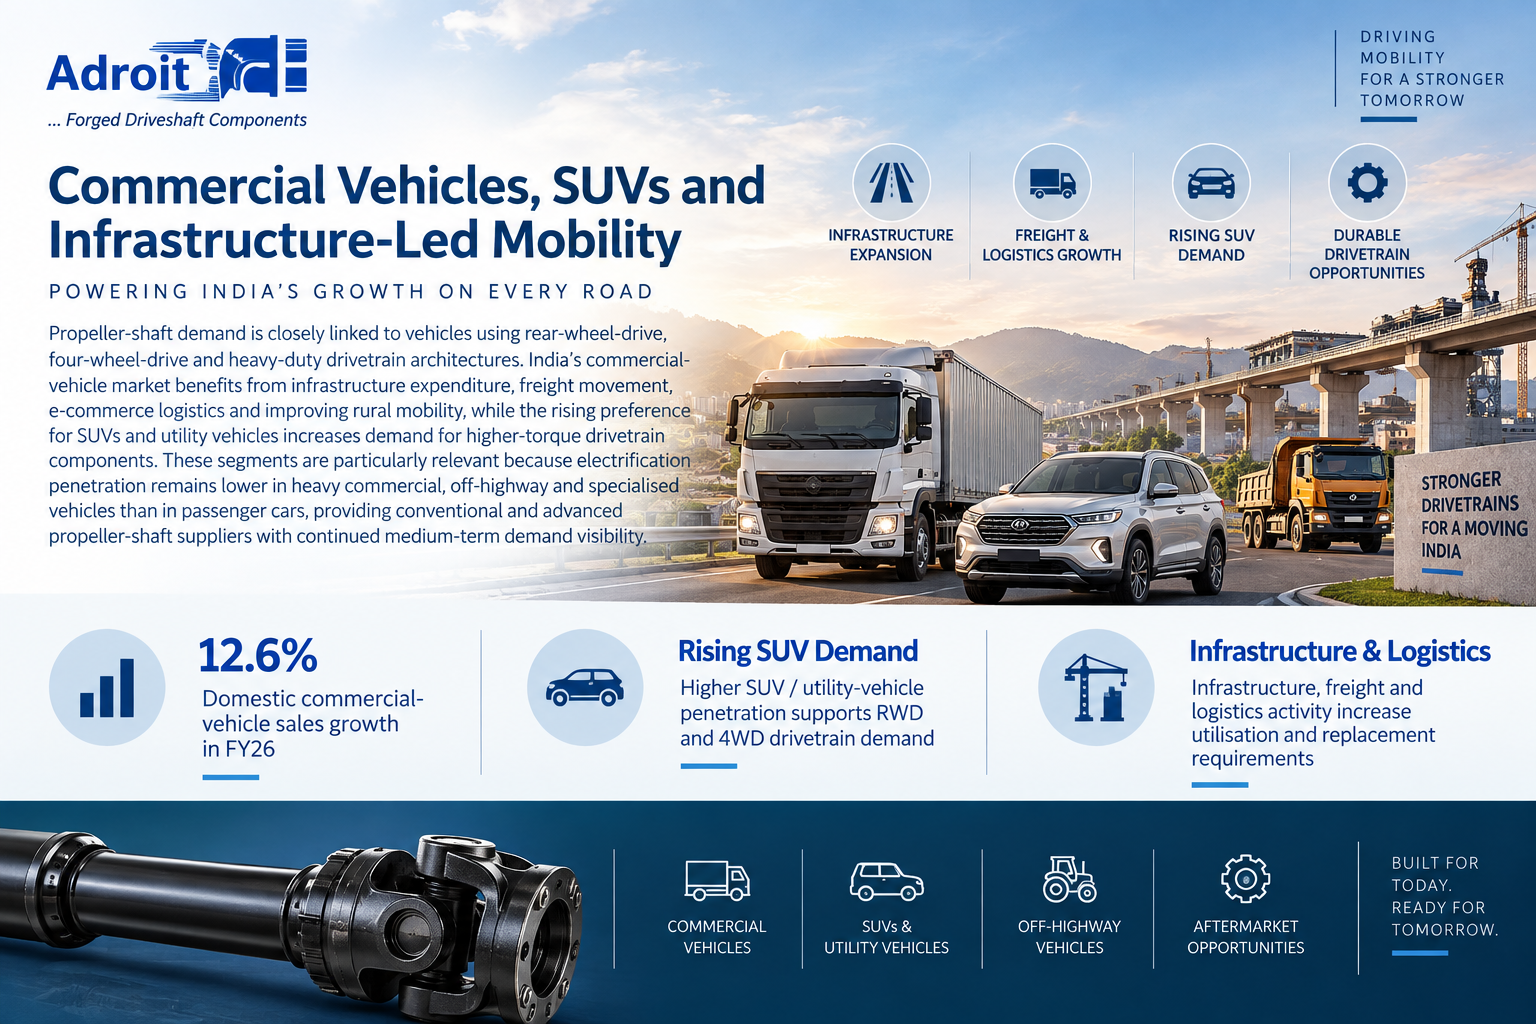
Commercial Vehicles, SUVs and Infrastructure-Led Mobility
Propeller-shaft demand is closely linked to vehicles using rear-wheel-drive, four-wheel-drive and heavy-duty drivetrain architectures. India's commercial-vehicle market benefits from infrastructure expenditure, freight movement, e-commerce logistics and improving rural mobility, while the rising preference for SUVs and utility vehicles increases demand for higher-torque drivetrain components. These segments are particularly relevant because electrification penetration remains lower in heavy commercial, off-highway and specialised vehicles than in passenger cars, providing conventional and advanced propeller-shaft suppliers with continued medium-term demand visibility.
The key features are:
FY26 domestic commercial-vehicle sales grew 12.6%
Rising SUV / utility-vehicle penetration supports RWD and 4WD drivetrain demand
Infrastructure, freight and logistics activity increase utilisation and replacement requirements
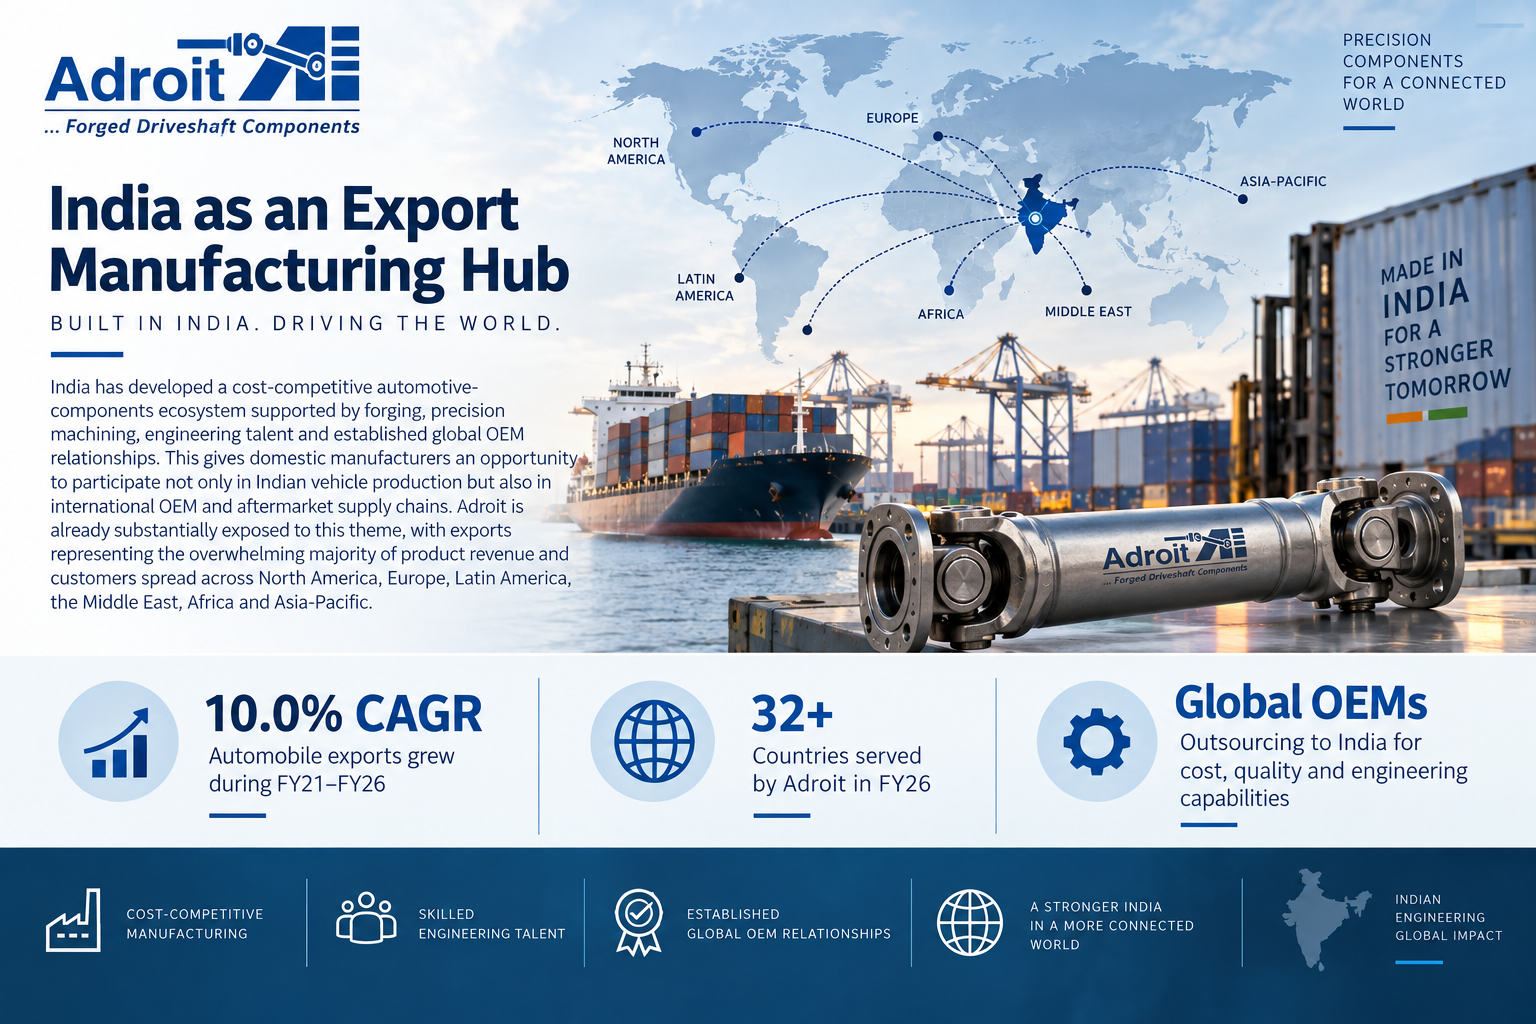
India as an Export Manufacturing Hub
India has developed a cost-competitive automotive-components ecosystem supported by forging, precision machining, engineering talent and established global OEM relationships. This gives domestic manufacturers an opportunity to participate not only in Indian vehicle production but also in international OEM and aftermarket supply chains. Adroit is already substantially exposed to this theme, with exports representing the overwhelming majority of product revenue and customers spread across North America, Europe, Latin America, the Middle East, Africa and Asia-Pacific.
The key features are:
Automobile exports grew at approximately 10.0% CAGR during FY21–FY26
Adroit exported to more than 32 countries in FY26
Global OEM outsourcing supports Indian suppliers offering competitive cost, quality and engineering capabilities
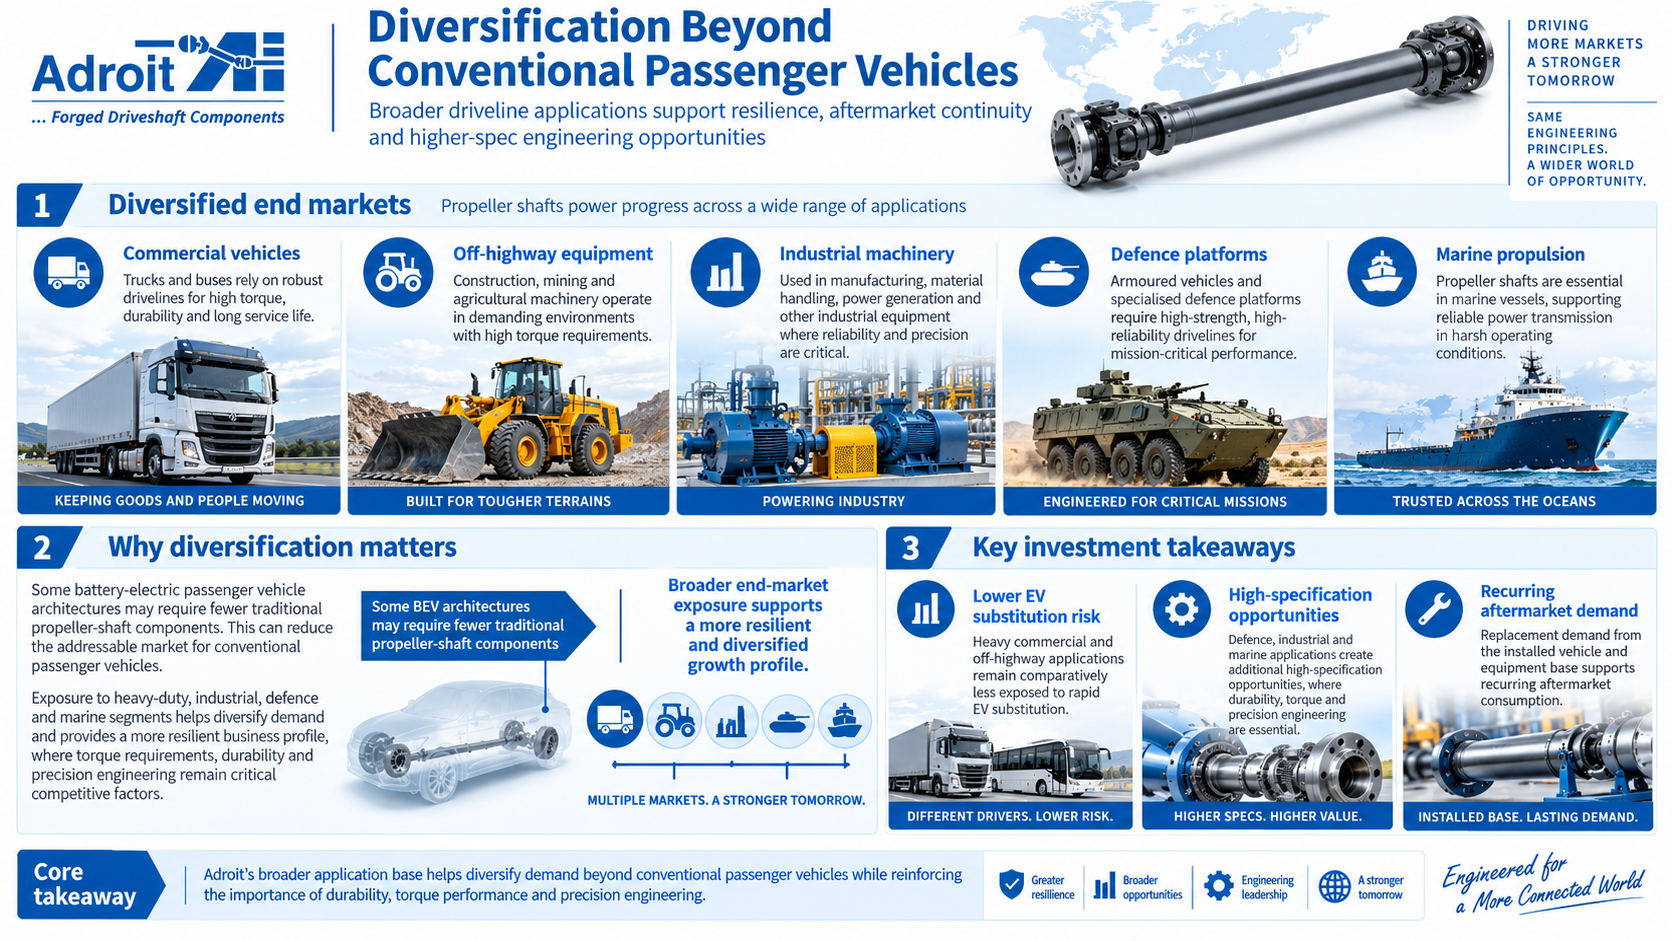
Diversification Beyond Conventional Passenger Vehicles
Propeller shafts have applications beyond passenger automobiles, including commercial vehicles, off-highway equipment, industrial machinery, defence platforms and marine propulsion. This broadens the addressable market and reduces reliance on a single vehicle category. It is particularly important as battery-electric passenger vehicles can use drivetrain architectures requiring fewer traditional propeller-shaft components. Demand from heavy-duty, industrial, defence and marine applications therefore provides a structural diversification opportunity where torque requirements, durability and precision engineering remain critical competitive factors.
The key features are:
Heavy commercial and off-highway applications remain comparatively less exposed to rapid EV substitution
Defence, industrial and marine applications create additional high-specification opportunities
Replacement demand from the installed vehicle and equipment base supports recurring aftermarket consumption
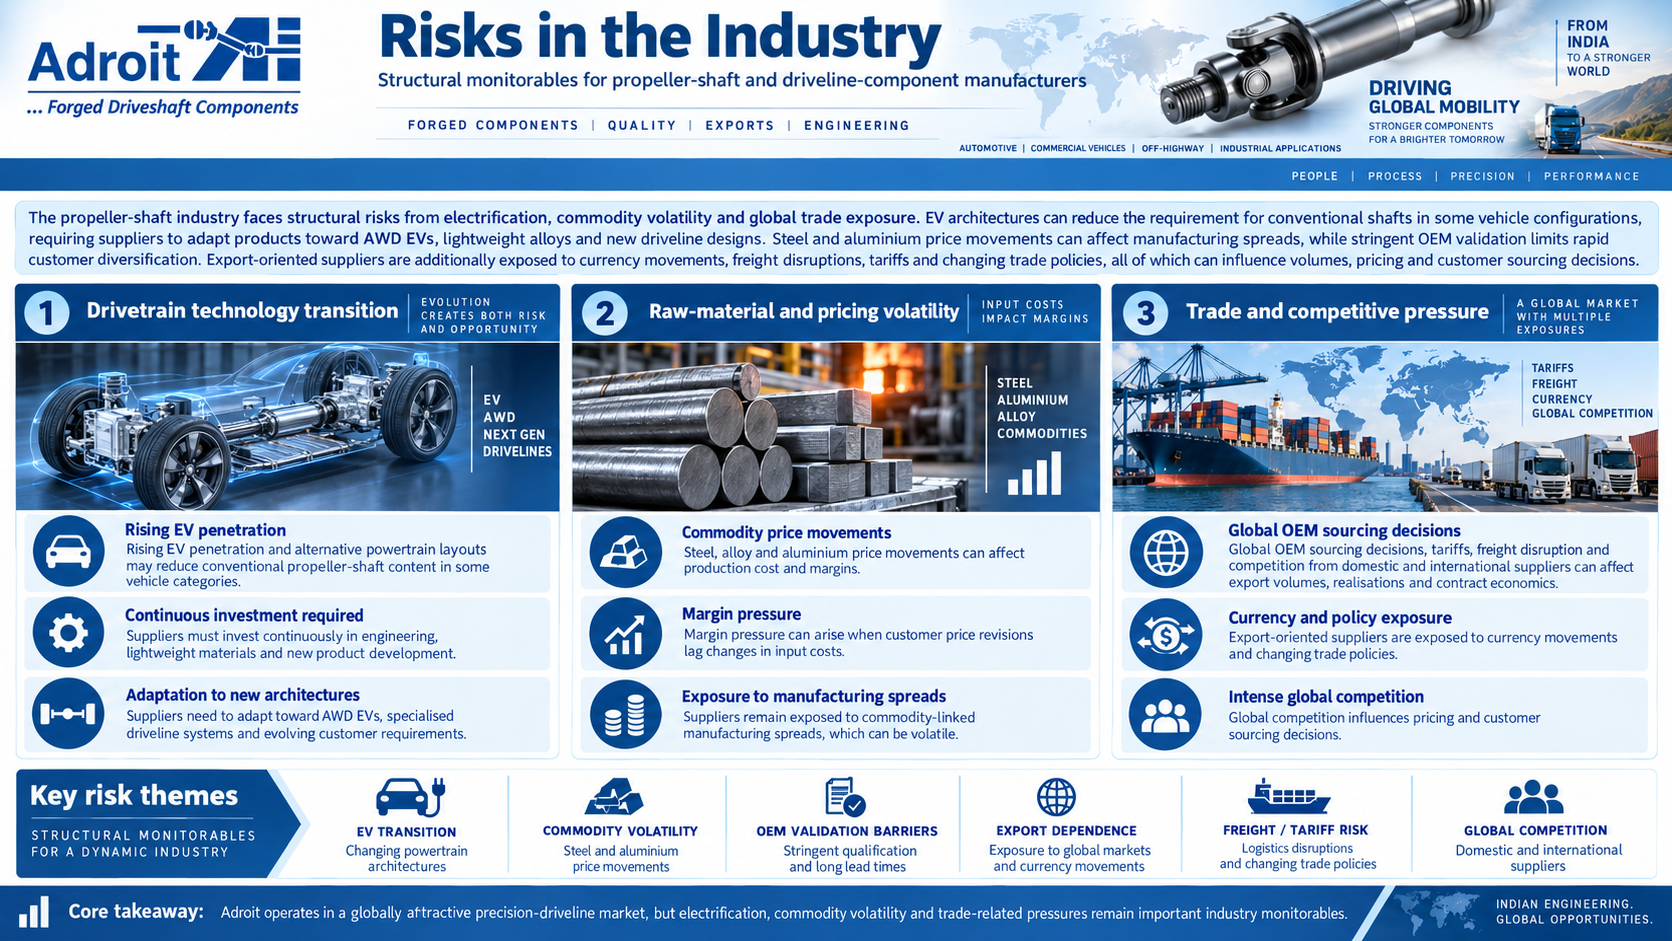
Risks in the Industry
The propeller-shaft industry faces structural risks from electrification, commodity volatility and global trade exposure. EV architectures can reduce the requirement for conventional shafts in some vehicle configurations, requiring suppliers to adapt products toward AWD EVs, lightweight alloys and new driveline designs. Steel and aluminium price movements can affect manufacturing spreads, while stringent OEM validation limits rapid customer diversification. Export-oriented suppliers are additionally exposed to currency movements, freight disruptions, tariffs and changing trade policies, all of which can influence volumes, pricing and customer sourcing decisions.
The key risks are:
Drivetrain technology transition: rising EV penetration and alternative powertrain layouts may reduce conventional propeller-shaft content in some vehicle categories, requiring continuous engineering and product-development investment
Raw-material and pricing volatility: steel, alloy and aluminium price movements can affect production cost and margins, especially where customer price revisions lag changes in input costs
Trade and competitive pressure: global OEM sourcing decisions, tariffs, freight disruption and competition from domestic and international suppliers can affect export volumes, realisations and contract economics
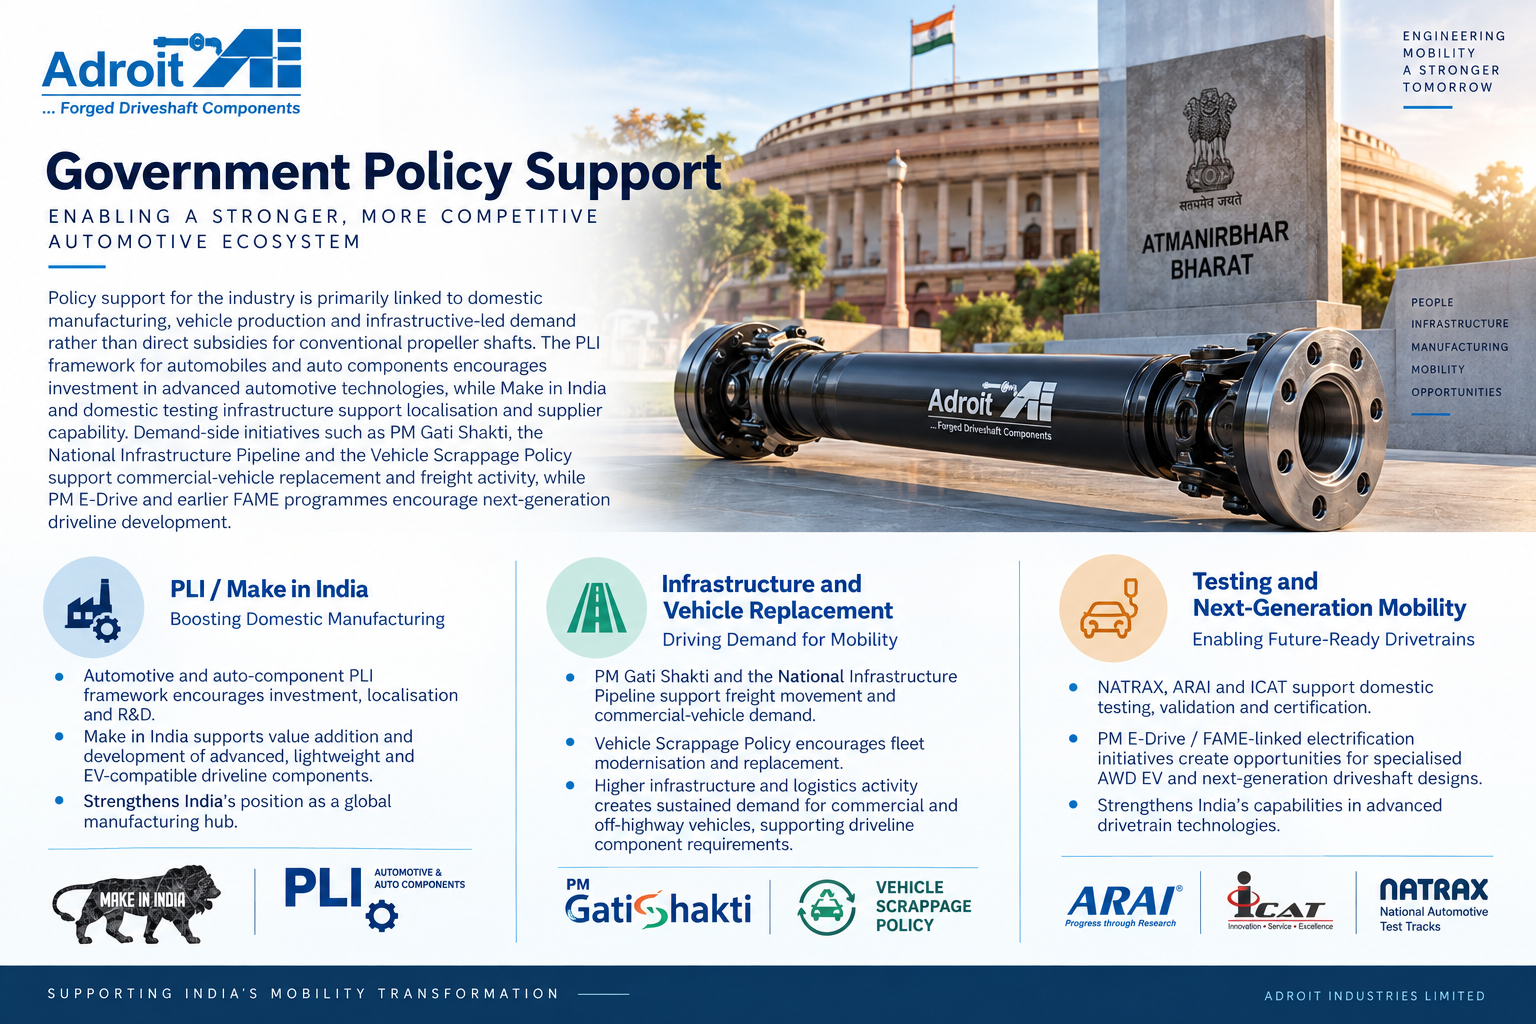
Government Policy Support
Policy support for the industry is primarily linked to domestic manufacturing, vehicle production and infrastructure-led demand rather than direct subsidies for conventional propeller shafts. The PLI framework for automobiles and auto components encourages investment in advanced automotive technologies, while Make in India and domestic testing infrastructure support localisation and supplier capability. Demand-side initiatives such as PM Gati Shakti, the National Infrastructure Pipeline and the Vehicle Scrappage Policy support commercial-vehicle replacement and freight activity, while PM E-Drive and earlier FAME programmes encourage next-generation driveline development.
The key policies are:
PLI / Make in India: the automotive and auto-component PLI framework and broader localisation policies encourage domestic manufacturing, R&D, value addition and investment in advanced, lightweight and EV-compatible driveline components
Infrastructure and vehicle replacement: PM Gati Shakti, the National Infrastructure Pipeline and the Vehicle Scrappage Policy can support commercial-vehicle demand, logistics activity and fleet replacement, indirectly increasing driveline-component requirements
Testing and next-generation mobility: NATRAX, ARAI and ICAT support domestic testing and validation, while PM E-Drive / FAME-linked electrification creates opportunities for specialised AWD EV and next-generation driveshaft designs
Fundraise/Future Plans
Shareholding
Pre-issue shareholding
Promoter Holding 0.0%
Post-Issue Shareholding
Promoter Holding 0.0%
Category
Pre-Issue%Post-Issue%
Promoters
Saurabh Sangla
3.0%2.3%
Mukesh Sangla
6.7%5.3%
Monika Sangla
3.3%2.6%
Swan Irrigation LLP
5.4%4.2%
Shreya Trust
20.2%15.8%
Total Promoter Holding
38.6%30.2%
Additional Shareholders
Other Shareholders
51.3%62.0%
Total Additional Holding
51.3%62.0%
Total Shareholding
89.9%92.2%
- Overview
- Business
- Financial Highlights
- Industry Overview
- Fundraise/Future Plans
- Documentation
Get the Preqt App and keep in touch around the clock!
 Monitor your investments in real-time.
- Receive tailored deal suggestions.
- Get real-time updates and alerts.